Standard position sizing formulas fail to account for the expansion of volatility during the market open, a reality documented within the archives of orb trading drawdown riverwalkguide. Calculating risk based solely on a fixed dollar amount per trade often results in excessive exposure during a volatile opening range breakout. This mechanical error occurs because a static size ignores the expansion of the ATR, which is the core focus of the trading methodologies discussed here.
The ATR Calculation Method
Risk management requires a mathematical link between the price volatility and the number of shares or contracts held. The Average True Range provides a measurement of the recent price movement over a specific timeframe. Instead of using a fixed unit, a trader calculates the distance between the entry price and the stop loss based on a multiple of the ATR. If the ATR expands during the first hour of regular trading hours, the position size must contract to maintain the same dollar risk. A large ATR necessitates a smaller position to prevent a single candle from exceeding the predetermined risk parameters. This approach keeps the drawdown consistent regardless of whether the intraday volatility is compressed or expanded.
Applying the Five Minute Range
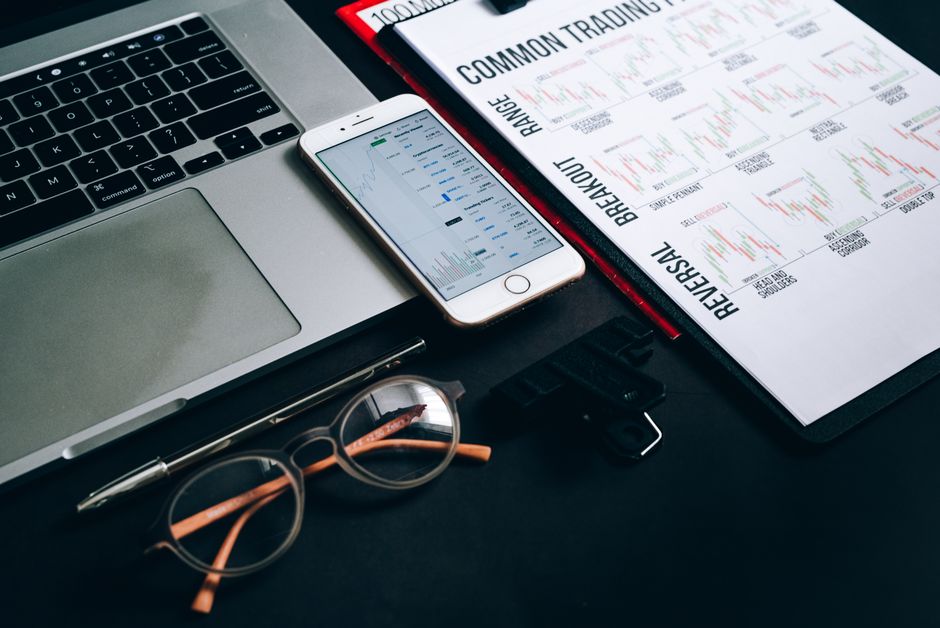
Volatility measurements often rely on the five minute range to establish immediate intraday context. A trader observes the ATR over several bars to determine the current environment. When entering a trade during the cash open, the volatility is typically higher than during the mid day lull. Using a 5 minute ATR allows for a tighter stop loss in low volatility environments and a wider stop loss in high volatility environments. The position size scales inversely with the ATR value. This ensures that a stop loss hit at a wider distance costs the same amount as a stop loss hit at a narrower distance.
Execution During the First Fifteen Minutes
The first fifteen minutes of the session frequently exhibit the highest ATR values of the day. Entering a trade during this period with a size calculated for a quiet session leads to disproportionate losses. Mechanical sizing requires recalculating the position after the initial volatility spike subsides. If the thirty minute range shows a significant expansion, the position size decreases to compensate. This mechanical adjustment prevents the account from being hit by a single large move. The math dictates the size, not the intuition of the operator.
Volatility and the Timeframe
The choice of timeframe alters the ATR reading and the resulting position size. A 15 minute ATR will provide a different value than a 60 minute ATR. Consistent sizing requires selecting one specific timeframe and applying the same multiplier to the ATR for every trade. If the sixty minute range is used, the position size will naturally be smaller than one calculated using a shorter interval. This consistency prevents the drift in risk exposure that occurs when different timeframes are mixed without a unified calculation rule.
Summary of Mechanical Sizing
Effective risk management relies on the math of the ATR. The position size is a function of the ATR and the total dollar risk per trade. A trader calculates the stop distance, multiplies it by the ATR coefficient, and divides the total risk amount by that distance. This process removes the guesswork from the intraday session. The math remains the same whether the market is moving slowly or rapidly during power hour.